

Perspectives Emerging Markets offers quarterly updates from our research team, providing in-depth analysis of economic developments, market trends, and investment opportunities in emerging economies.
Fourth quarter 2026
Number in focus
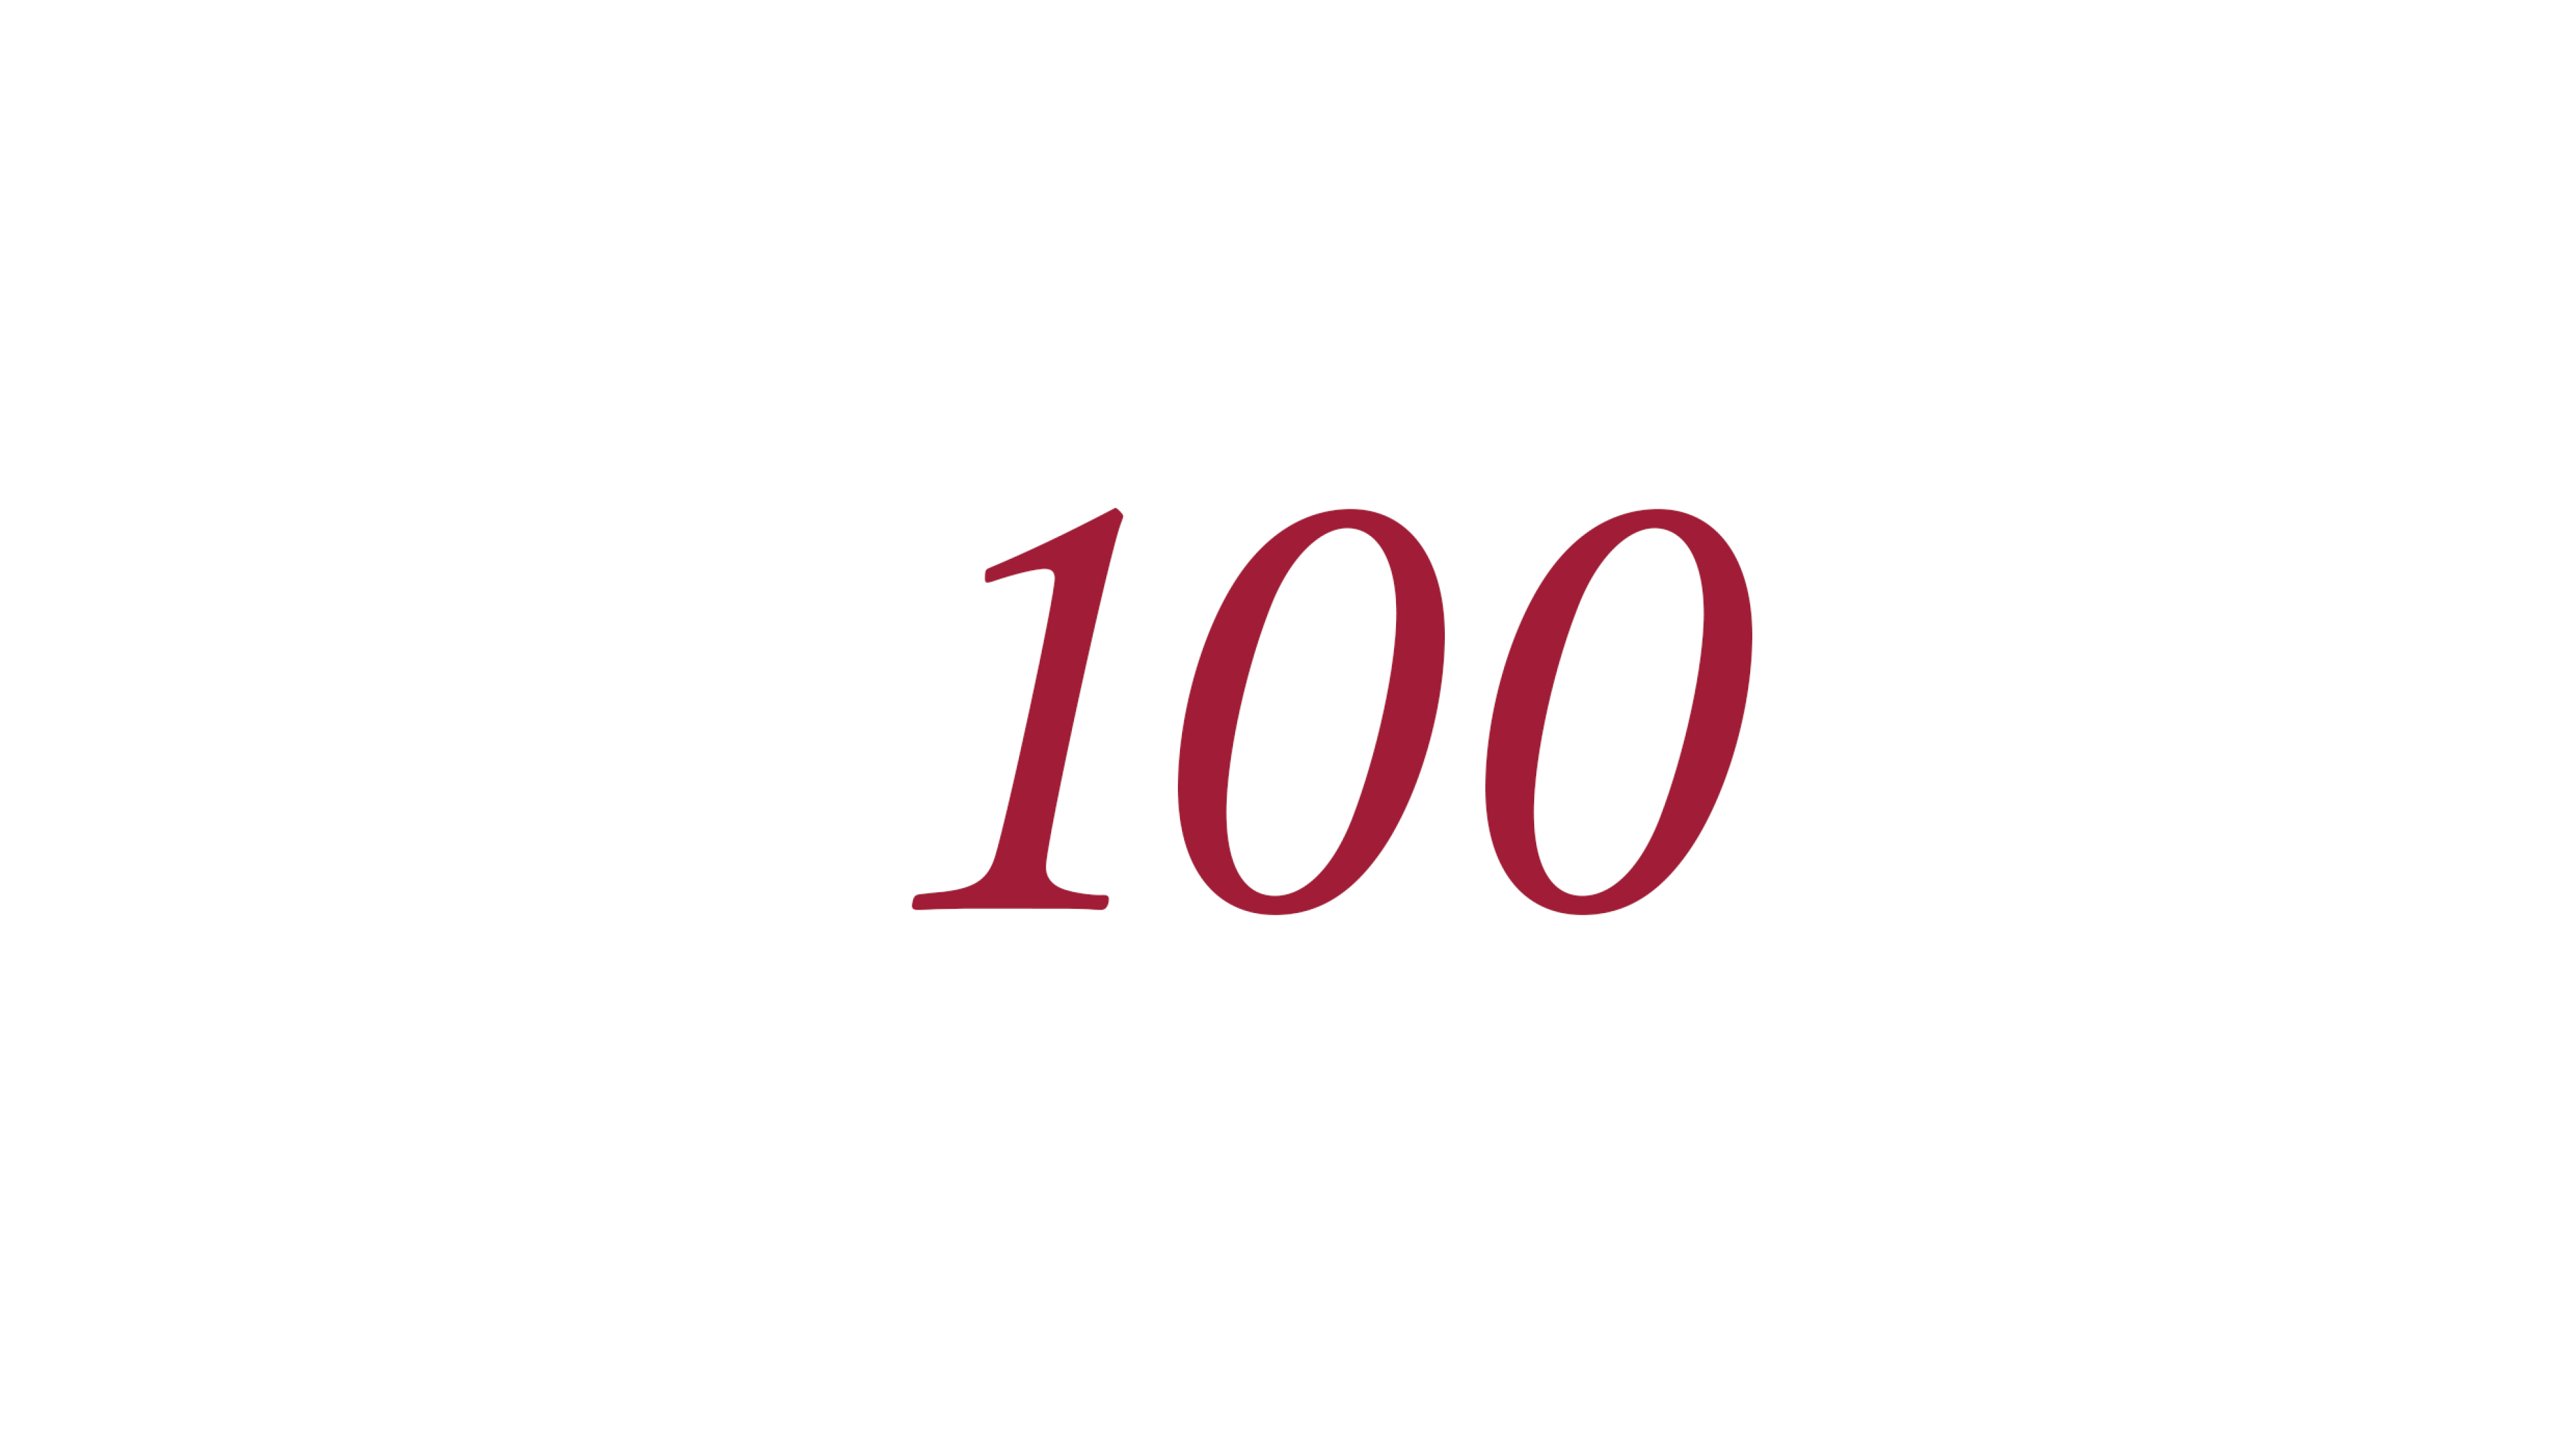
Disruptions to Saudi oil pipelines and more robust demand from China have pushed the oil price back above USD 100 per barrel. Should the situation escalate further, there is greater upside potential with corresponding inflation risks for the global economy. If this downside scenario does not occur, however, we expect oil prices to again fall below USD 100. Physical supply remains solid despite the disruptions, supported by increased shipments from non-Gulf states and an increase in bypass transport. As the current situation is not sustainable over the long term, we expect a diplomatic rapprochement in the medium term and a corresponding easing of price pressure.
Chart in focus
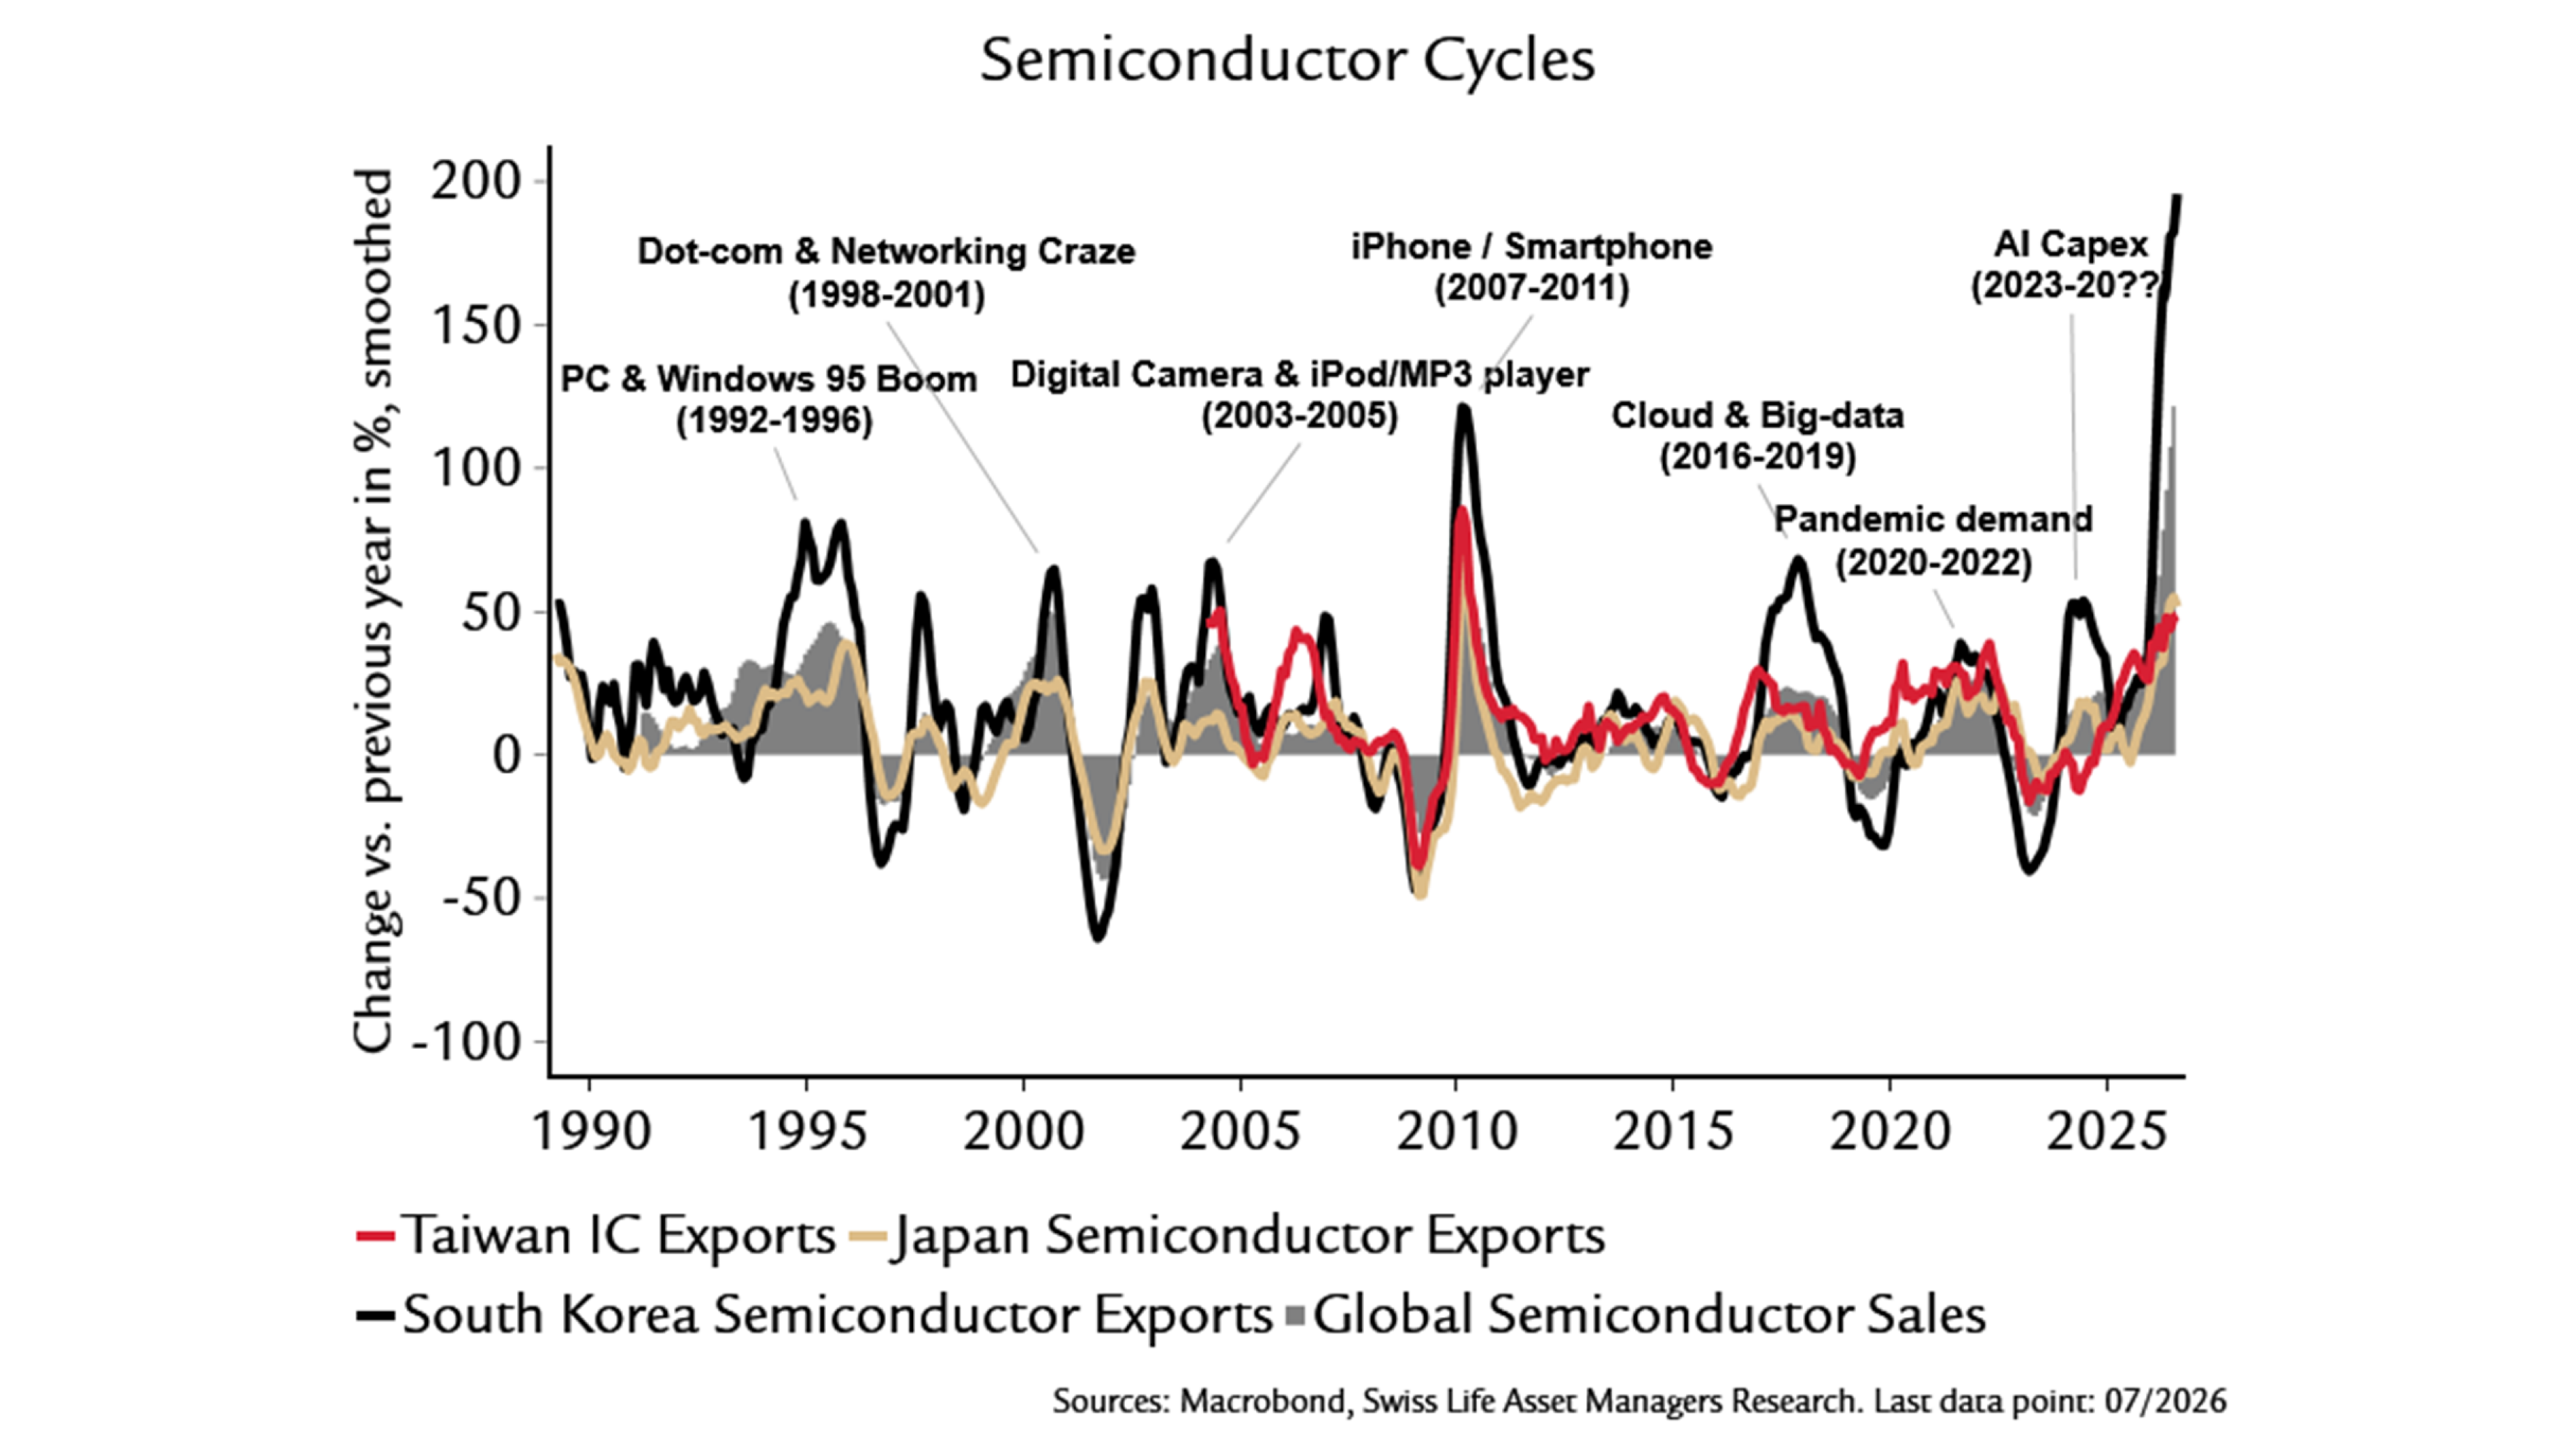
Emerging markets are at the heart of the AI hardware supply chain and are therefore particularly benefiting from the current AI boom. However, in the past, semiconductor cycles were usually limited to two to three years. It cannot therefore be ruled out that the current cycle will also end earlier than expected. However, there are several factors that suggest it will last longer. Technology companies have long-term plans for their AI investments and have concluded corresponding supply contracts. In addition, the spread of AI is still in its infancy. In contrast to previous technology cycles, there is no clear saturation point so far as applications and computing demand continue to grow.